Beyond the Monthly Fee: Understanding the True Cost of Condominium Ownership
Condominiums Ian Kasman November 6, 2026
Condominiums Ian Kasman November 6, 2026
Imagine finding a condominium that seems to offer everything you’re looking for: beautiful views, an appealing floor plan, attractive finishes, and a location you love. The asking price is within your budget, and the monthly association fee seems reasonable.
But how much do you really know about the building?
Unlike a single-family home, condominium ownership involves shared financial responsibilities for the building and its common elements. The property's condition, its association's finances, and the costs of maintaining and operating the building can substantially affect both the expense of ownership and future marketability. In Cincinnati, many established condominium buildings are now several decades old, making maintenance histories, capital improvement plans, and reserve funding especially important. These factors deserve as much attention as the residence itself.
Monthly condominium association fees can vary substantially, even among properties that appear similar in size, location, or amenities. It's tempting to assume that a lower fee represents better value. Sometimes it does, but the amount alone tells us little about how responsibly a building is maintained or whether its association is adequately preparing for future expenses.
Consider three hypothetical situations:
• In one building, high monthly fees accompany a significant capital improvement project, such as elevator modernization or the replacement of major mechanical systems. Even with substantial regular contributions, owners may still face additional costs, so it’s worth understanding how the project is funded.
• In another, monthly fees are modest, but an aging roof may require replacement. Without sufficient reserves or an established funding plan, owners could face a special assessment or an increase in regular fees.
• A third building may have comparatively high fees but also a documented reserve study, a consistent funding program, and a comprehensive package of services and amenities. Its ownership costs may be more predictable, although continued financial oversight remains important.
None of these situations, considered in isolation, tells us which condominium represents the best purchase. The relevant questions are what the fees cover, how the funds are managed, and what financial obligations may lie ahead.
One of the most important elements of condominium due diligence is the association's reserve funding. Operating expenses, including utilities, insurance, routine maintenance, and management, are generally paid through the annual operating budget. Reserve funds are intended to help cover major repairs and replacements as building components reach the end of their useful lives. Depending on the property, those components may include roofs, elevators, exterior walls, balconies, mechanical equipment, windows, and other common elements. A substantial reserve balance can be reassuring, but the amount alone is not a reliable measure of financial strength.
Consider two hypothetical buildings anticipating a $400,000 elevator modernization. One has $350,000 in reserves; the other has $75,000. At first glance, the first association appears better prepared. But it may also face substantial roof and exterior maintenance, while the second may have recently completed other major capital projects and established a defined plan to fund the elevators.
A professional reserve study can help clarify that relationship. It typically assesses major common components, estimates their remaining useful lives and replacement costs, and models the contributions needed to fund future expenditures. It is a planning tool, however, not a guarantee: its usefulness depends on the quality of its assumptions, the association's willingness to follow its recommendations, and how regularly it is updated.
Ohio law generally requires condominium associations to budget adequate reserves for major capital repairs and replacements, subject to certain exceptions. These include an annual written waiver approved by a majority of the unit owners' voting power and provisions in the association's governing documents that restrict assessment increases without an owner vote. Unlike some states, Ohio does not prescribe a uniform condominium resale disclosure package containing all the financial and operational information a purchaser may wish to review. Although associations are required to maintain certain records, buyers should identify the relevant documents early and ensure that their purchase agreement provides sufficient time and appropriate provisions for reviewing them.
Even responsibly managed condominium associations sometimes need to levy special assessments. Major capital projects can be difficult to predict precisely: construction costs change, unexpected deterioration occurs, and necessary improvements may exceed the amounts originally budgeted. An assessment does not automatically signal poor management. In some cases, undertaking an expensive repair demonstrates responsible stewardship of the building.
The more useful questions are why an assessment is necessary, whether the underlying issue has been adequately investigated, and whether the proposed funding is likely to address the obligation. Deferred maintenance deserves particular scrutiny: postponing essential work may keep monthly fees lower in the short term, but it can increase eventual repair costs and introduce uncertainty for future owners. Meeting minutes, engineering reports, capital plans, and discussions of proposed projects can therefore be as important as current financial statements. Together, they offer a fuller picture of how an association identifies and manages its obligations.
Condominium associations generally maintain a master insurance policy covering specified portions of the property and its common elements. Individual owners typically need separate coverage for personal belongings, liability, and certain interior improvements or building components. The precise allocation of responsibility depends on the association's governing documents and the terms of the applicable policies.
Buyers should understand not only the master policy's coverage limits but also its exclusions, deductibles, and the circumstances under which an owner may be responsible for part of an insured loss. Insurance costs affect association budgets, too: significant premium increases or changes in coverage may ultimately influence monthly fees or other owner obligations. They can also affect financing eligibility.
Mortgage lenders may evaluate the condominium project itself, not merely the individual buyer and residence. A building that meets the standards of major loan programs is often described as 'warrantable.' Lenders commonly consider the association's budget and reserve contributions, owner delinquency rates, pending litigation, insurance coverage, deferred maintenance, and whether a single entity owns a large share of the units.
Those standards are also tightening. For condominium projects subject to applicable full project-review requirements, Fannie Mae and Freddie Mac are increasing the minimum annual reserve allocation from 10% to 15% of budgeted assessment income, effective for mortgage applications dated on or after January 4, 2027. Qualifying reserve studies may provide an alternative, subject to specific requirements. These standards can affect financing eligibility even when the individual unit and borrower otherwise qualify.
A condominium that does not meet an applicable lender's or investor's project standards may still be purchased with cash or alternative financing, but the pool of future buyers could be narrower. That matters even to someone paying cash today: a building's financial condition, insurance coverage, and financing eligibility can influence its marketability years later.
Condominium due diligence should extend beyond the unit inspection and the purchase agreement. I recommend reviewing the following, with the understanding that the appropriate scope depends on the property and transaction:
• Association budget and financial statements: What are the regular operating expenses, and how closely do actual expenditures match the budget?
• Reserve balances and reserve studies: What major replacements are anticipated, and how are they being funded?
• Planned capital improvements: Are there significant projects underway, proposed, or under consideration?
• Special assessments: Have assessments been approved, discussed, or recently completed? What obligations might transfer to a purchaser?
• Board and association meeting minutes: What maintenance issues, financial concerns, or recurring disputes have been discussed?
• Master insurance coverage: What does the association insure, what deductibles apply, and what coverage must owners obtain individually?
• Financing eligibility: Are there known project-related concerns that could limit conventional mortgage options?
• Litigation and delinquencies: Is the association involved in any lawsuits, and what share of owners are behind on their fees?
• Governing documents and ownership restrictions: What rules apply to renovations, rentals, pets, parking, and other aspects of ownership?
For sellers, assembling these materials early can help buyers evaluate the property more efficiently and reduce uncertainty during a transaction. Sellers should confirm applicable disclosure requirements and avoid presenting estimates or preliminary plans as settled facts. For buyers, the goal is not to find a building without expenses or future obligations. No such building exists. The goal is to understand those obligations well enough to make an informed decision.
Condominium living can offer extraordinary advantages: desirable locations, distinctive views, reduced responsibility for routine exterior maintenance, shared amenities, and the convenience of leaving a residence unattended for extended periods. Those benefits have real value. But ownership costs extend beyond the purchase price, mortgage payment, and current association fee. They also reflect the building's condition, anticipated capital needs, responsibilities shared among owners, and the quality of the association's financial planning. Two residences may look quite similar while carrying substantially different long-term costs.
My thanks to Stef Adams of CrossCountry Mortgage for her informative presentation on recent changes to condominium lending and insurance requirements, which contributed to this article.
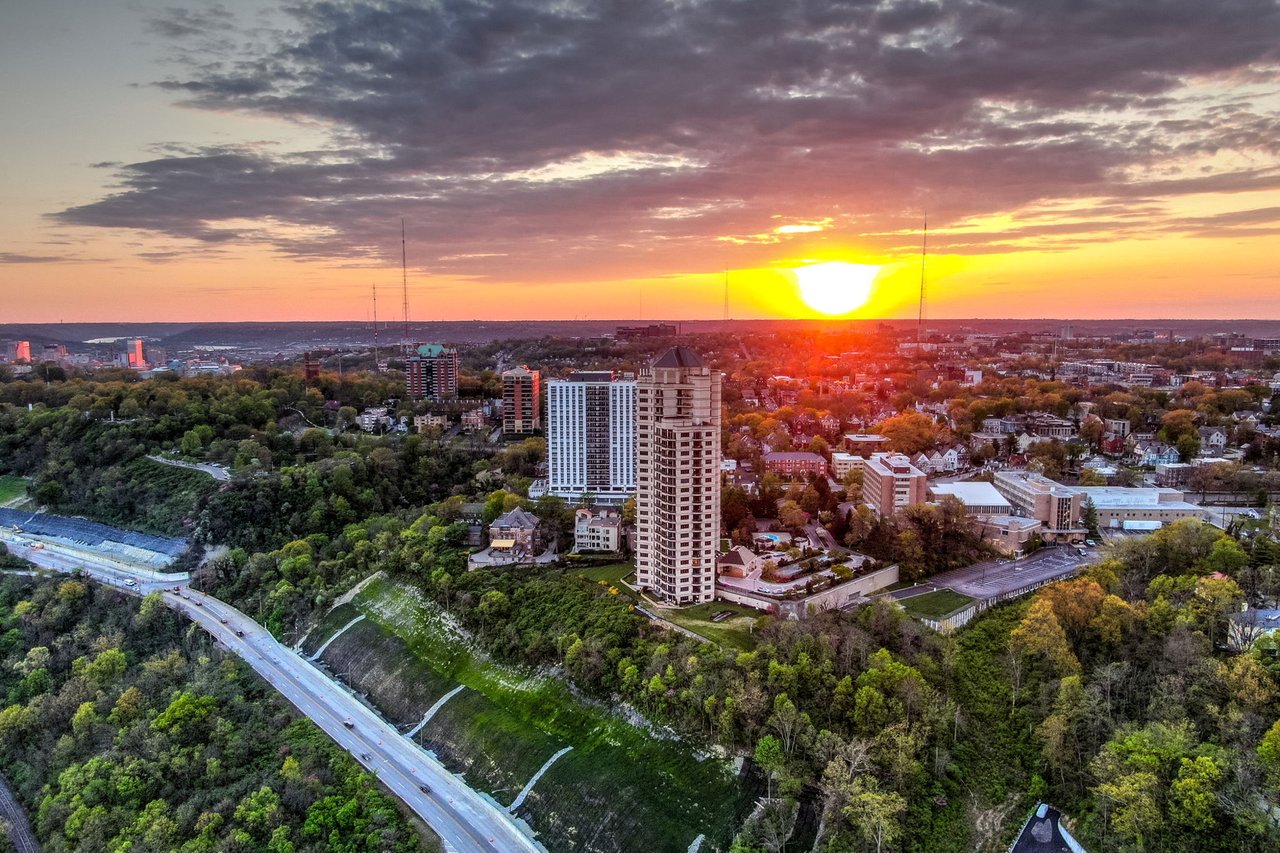
Photograph by Tim Spanagel.
This article is for general information only and is not legal, tax, insurance, or lending advice. Buyers and sellers should consult qualified professionals about their specific situation.
Editorial note: The ideas, analysis, and conclusions expressed in this article are my own. ChatGPT (OpenAI) and Claude (Anthropic) assisted with organization, structure, and editorial refinement. I reviewed the final article and take responsibility for its content.
• Ohio Revised Code §5311.081: Powers and Duties of Condominium Association Boards
Reserve budgeting requirements and permitted exceptions.
• Ohio Revised Code §5311.09: Unit Owners Association Records
Association recordkeeping obligations, including financial records and meeting minutes.
• Ohio Revised Code §5311.091: Examination of Books, Records, and Minutes
Unit owners’ rights to examine association records, subject to statutory limitations.
• Fannie Mae: Lender Letter LL-2026-03 (March 18, 2026)
Changes to condominium project eligibility, reserve funding, and insurance requirements.
• Freddie Mac: Bulletin 2026-C (March 18, 2026)
Updated condominium project review and reserve funding standards.
Stay up to date on the latest real estate trends.
Newsletters
Condominiums
Newsletters
September in Cincinnati: Prices Level Off, Competition Doesn’t
Ownership Strategy
Newsletters
This September: Timeless Style
Ownership Strategy
Market Statistics
Updated quarterly with the latest Hyde Park housing trends, pricing, and market activity.
Ownership Strategy
Continuity, Flexibility, and Long-Term Ownership Planning

Utilities
Understanding the Open Market and Energy Choice
Whether you're buying your first home, looking to upgrade, or downsize, contact us to help you with your next Real Estate sale or purchase!